How to Extract Yield From Extreme Funding from Altcoins (ARC)
Extreme positive funding is rare. Persistent extreme positive funding is even rarer.
$ARC is one of the cleanest examples right now of a leverage-dominant structure where funding has been structurally positive for months. In this article I’ll explain the delta-neutral play and how you can farm these extremes.It’s not bulletproof. It’s risky. Especially on a narrative-driven coin with straight up cartel PA.
Just a note before we begin. The edge on this coin has mostly been on the long side for months. At the same time, fading every directional pump into S/R when OI was skyrocketing worked great too. That’s mainly what I traded. But you could’ve been doing both. Riding the long side and running the trade I’ll explain below. Basically… just collecting the funding.
Understanding the Structure of $ARC
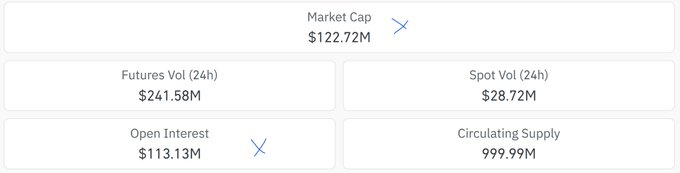
For months OI vs MC on $ARC was basically 1:1. Pure leverage structure. Now dynamics are slowly shifting. OI pulling back a bit while market structure looks like it’s breaking higher.
Before execution, understand what makes this unique.
Market Cap ≈ Open Interest. Basically 1:1 for three months, sometimes derivatives even overshooting spot. Funding repeatedly spiking 200-1000% APR. Spot liquidity centralized on one exchange.. you guessed it, Gate.io. Perp dominance on Bybit. Directional longs mainly chasing there. That’s where positive funding is richest and that’s where you want to think about shorting.
What does this tell us? Price discovery is leverage-driven. Perps aren’t hedging spot demand. They’re driving it.
That’s the foundation of the opportunity.

~63% of supply sits on Gate. That’s a massive exchange concentration. My favorite cartel place.
When ~63% of supply sits on one exchange and OI is almost equal to the entire market cap, you basically have a derivatives market as big as the token itself sitting on thin, centralized spot. That means it doesn’t take much perp leverage to push price higher. Market makers hedge into a shallow spot book, price moves fast (You can see this on chart, when this decides to move it literally runs).

Open Interest skyrockets on every move up and bleeds on every move down. Textbook rotations.
Leverage dictates here.
Price goes up → more longs chase → OI expands → perps trade at premium → funding stays high. Not organic demand. Leverage driving price. Arb isn’t frictionless either. Thin depth, spreads, cross-exchange friction. So funding doesn’t compress quickly.

Net long market needs to be studied
The Core Idea: Delta Neutral Funding Capture
When funding is extremely positive: Longs pay. Shorts receive.
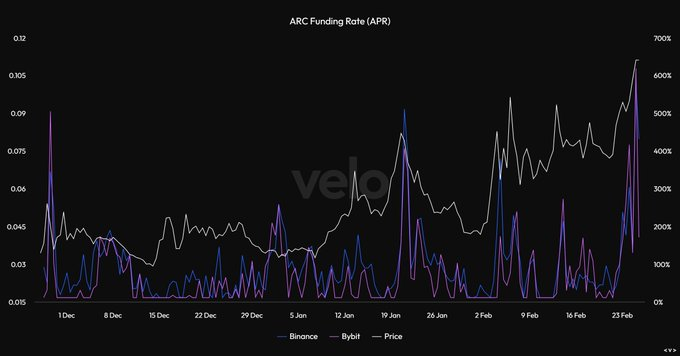
This is very farmable, nice funding. Keep in mind on Bybit it’s every 4 hours now, but at the beginning it used to be every 1 hour.
Instead of taking directional risk, you can:
- Buy spot (primarily Gate)
- Short perpetual (Bybit shows highest funding spikes)
- Match notional size
- Collect funding
Net directional exposure ≈ 0
(Execution isn’t perfect. Liquidity thin. Spreads annoying. Timing never clean. And I’m not some quant catching the most beautiful basis entry known to mankind.)
At the core it’s simple. You’re collecting the funding.
Step-By-Step Execution Framework
Step 1 Confirm Structural Funding
You’re not trading one funding spike.
You want:
- Sustained positive funding
- Repeated spikes
- Elevated OI
- No persistent negative resets
$ARC fits this profile.
Step 2 Assess Liquidity & Venue Dynamics
Spot:
- Gate dominates volume
Perps:
- Bybit shows most aggressive positive funding spikes
Manual execution is possible, but precision matters.
Step 3 Entry Timing
Best entries usually happen during:
Sharp corrective pullbacks.
Into strong S/R.
While funding is still elevated and OI is either skyrocketing or starting to decline.
A lot of the time you’re getting filled right into profit-taking zones (Limit orders there).
Step 4 Position Construction Example
Spot buy: $1,000
Perp short: $1,000
“Fully hedged”
Maintain sufficient margin buffer to survive volatility on pers.
Trade Example (3-Month Hypothetical)
Assume:
Average funding = 250% APR
Holding period ≈ 90 days
250% APR ≈ 0.68% per day.
Over 90 days that’s ≈ 61% yield.
On $1,000 that’s roughly $610 in funding.
Even if funding averages only 150% APR:
≈ 37% over 3 months → about $370 on $1,000.
The math is simple.
Even at 150–250% average funding, you’re looking at 30–60% over three months.
That’s why persistent funding structures are interesting.
Key Risks and Final Take
$ARC is low float and leverage-dominant. When OI is comparable to market cap, moves get exaggerated.
A sharp wick higher can stress or liquidate your short leg if margin isn’t managed properly. Delta-neutral ≠ risk-free.
Buffer is mandatory.
Persistent 200–600% APR is not guaranteed. The edge only exists while the imbalance exists.
Extreme funding isn’t just a sentiment signal
Right now $ARC represents:
• Exchange-concentrated supply
• Leverage-driven price discovery
• Reflexive funding dynamics
You can:
Chase direction
Fade exhaustion
Or systematically monetize the imbalance via delta-neutral positioning
You might ask, why take this trade for “a couple bucks” while carrying risk?
Fair question.
You can scale it. 5k–10k feels reasonable. Anything above that gets shaky (at least from what I saw in the books).
And yeah… free money. Until it’s not :D. Also you can try different trading than gambling into two directions.
Thanks for reading.